The Sofa, the Scan and the Six-Hour Detour: Insuring a Family-First India Trip in 2026
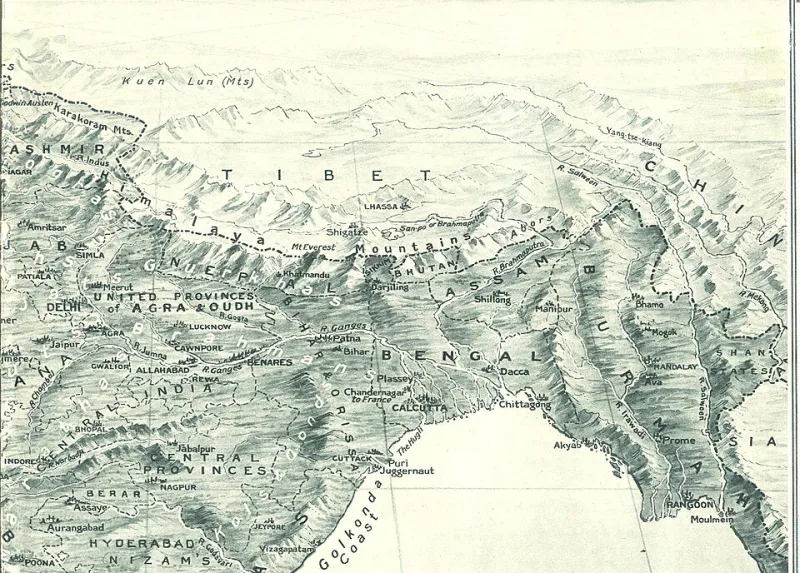
Photo: RNRCTG, CC0, via Wikimedia Commons
A British-Indian family trip to India is rarely one destination. It is three weeks, two cities, one ancestral village, a cousin's wedding and a spare room at the parental home. That is a wonderful shape for a holiday, but it is an awkward shape for a standard UK travel insurance policy. Most policies are built around the idea of a hotel, a beach and a direct flight. Your trip may be built around a sofa, a scan appointment and a six-hour detour to see an aunt in another state.
In 2026, comparison sites are better than they used to be, but they still ask questions that do not quite fit family-first travel. The trick is not to find the cheapest quote. It is to find a policy that recognises the trip you are actually taking.
Start with the guest list, not the quote
Before you open a price comparison tab, write down who is going, how old they are and what their health looks like. Insurers price risk, not sentiment. If you are travelling with a parent who has diabetes, a grandparent who has had a stent, or a partner who is waiting for a follow-up scan, that information belongs in the medical screening process, not in a footnote.
Also list the states you plan to visit and the number of nights you will be away. A policy may cover India as a whole, but some activities and regions carry exclusions. Check the Foreign, Commonwealth & Development Office travel advice for the areas you plan to visit, and make sure your policy does not quietly exclude anywhere you are going. If your trip includes a stopover in Dubai or Doha, mention it too. Insurers care about the whole journey, not just the bit with the chai.
The parental home is not a hotel, and your policy knows it
Staying with family is one of the joys of an India trip. It is also one of the most common insurance blind spots. Many UK policies will cover a stay with friends or family, but the baggage and theft sections can shrink when you are not in commercial accommodation. There is no hotel safe, no 24-hour reception and no formal record of what was in the room.
Read the wording on 'secure accommodation' and 'unattended baggage'. A phone left charging in a cousin's living room may count as unattended. A suitcase in a spare room may not meet the policy's idea of secure storage. Keep passports, cash, jewellery and gadgets with you where possible. Ask your host for a locked cupboard, but do not assume the policy will treat it like a hotel safe. If you are carrying wedding gifts or family valuables, check the single-item limit before you pack.
Declare the tablets, the ticker and the taxi-to-hospital
Pre-existing medical conditions are where cheap policies go to die. If a parent has a heart condition, high blood pressure, asthma or reduced mobility, declare it. The medical screening line is not a chatbot to beat. It is the part of the policy that decides whether a hospital bill in India will be paid. Have a recent GP summary and a list of prescription medicine names and doses to hand.
Age limits matter too. Some UK policies stop medical cover at 75 or 80, or charge a significant premium for older travellers. If you are travelling with older relatives, compare policies that specialise in senior travel and check the emergency assistance arrangements. A medical evacuation from a smaller city to Delhi, Mumbai or Chennai, and then back to the UK, can be expensive. Look for clear cover for medical repatriation and air ambulance, and check the excess. The NHS does not follow you to India, and a GHIC card is not a substitute for travel insurance.
The gadget gap and the three-week suitcase
Standard baggage cover often has a low single-item limit. A laptop, a camera and a phone can easily exceed it. Check whether gadgets are covered as valuables, whether they need to be listed separately, and whether proof of purchase is required. Keep receipts and serial numbers in your phone and in the cloud. If you are checking a bag on a domestic flight, pack essential medication in your hand luggage and keep a change of clothes with you.
Baggage delay is another useful section. It will not rescue a ruined holiday, but it can cover the basics if your suitcase takes a detour via another city. Keep receipts for emergency purchases and report the delay to the airline before you leave the airport. Insurers will ask for that paperwork later.
When the trip is longer than the policy's patience
A three-week trip across several states may fit a single-trip policy, but check the maximum trip length. Annual multi-trip policies often cap individual trips at 31 days. If you are staying for six weeks, say so. If you are travelling with relatives who live in India, remember that your policy covers you, not them. They need their own arrangements.
Some policies also ask for your main destination and may treat multi-country trips differently. Be honest about the shape of the journey. A policy bought for a beach holiday in Goa may not behave well when the claim involves a domestic flight to Kolkata and a hospital in a tier-two city.
The pre-payment checklist
Before you pay, call the insurer and ask three questions. Does the policy cover a stay with family in a private home? Does it cover the states and stopovers on your itinerary? Does the medical cover include the older travellers in your group, with their conditions declared? Get the answers in writing if you can, and save the policy documents on your phone and in a paper folder.
Check the emergency phone number, the excess and the claims process. A good policy is not the one with the lowest headline price. It is the one that still makes sense when the itinerary includes a sofa, a scan and a six-hour detour. Buy for the trip you are actually taking, not the package deal you almost booked.